
Education Financing — for schools, academies and training providers
The course fee becomes affordable — and you get the full amount.
Enrolments rarely fail because of the programme, but because of the figure on the invoice. Cashare finances your students’ course fees: “maybe next year” turns into a monthly instalment — and an enquiry into an enrolment. You receive the full amount in a single payment. Your student pays the instalments to Cashare. No collection, no default risk (standard model, without a guarantee), and no fee per enrolment.
Set up in a few minutes — no setup fee, no commitment, no minimum volumes.
A Swiss platform since 2008. Audited by PricewaterhouseCoopers, licensed as a lender, member of ZEK/IKO, affiliated with the SRO PolyReg. Data held in Switzerland.

 ZEK · IKOMember
The model
Financing built into your own offer
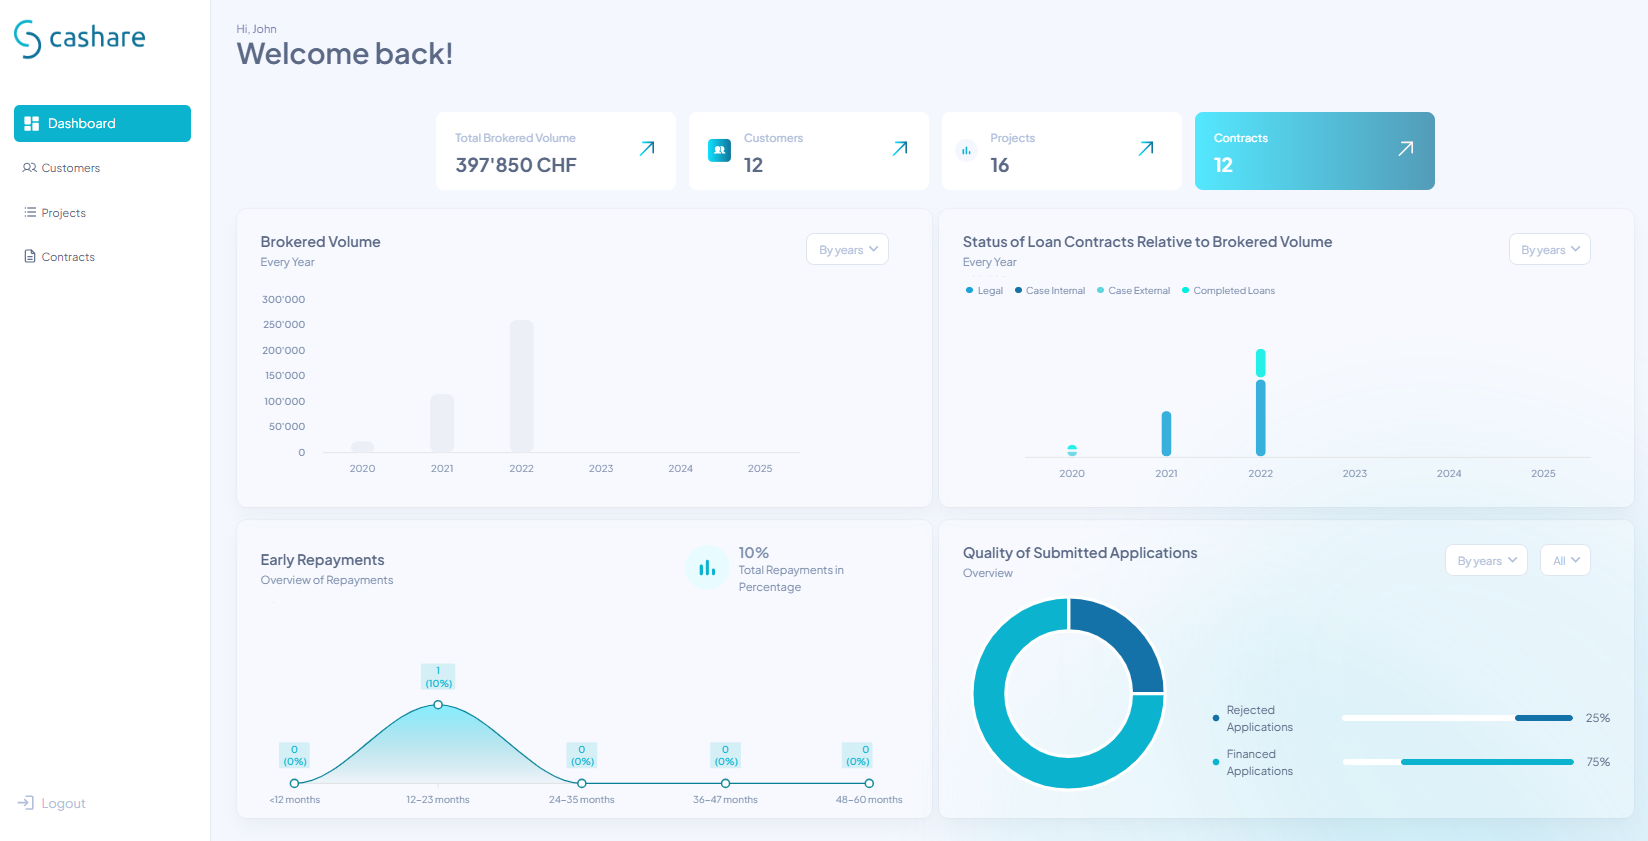
The financing sits where your prospect decides: next to the enrolment form. For example, someone who wants the CHF 12’000 programme but does not have CHF 12’000 available sees a monthly instalment instead — and applies on your own landing page at Cashare, not with you in the meeting.

What you get
- More closed deals — your customer can pay for your product or service in instalments. The deal no longer fails on the total amount; it becomes a monthly instalment that fits the budget.
- The full amount to your account, 14 days after successful funding. You are named as the payee in the loan agreement.
- No default risk (standard model, without a guarantee) and no dunning — the instalments are a matter between your customer and Cashare.
- Your brand, your experience — a white-label integration that looks and feels like your own product. From Scale; with Grow under Cashare branding.
- Fast integration — Grow is ready to go without an IT project.
What your customer gets
- Your product or service in instalments, tailored to their needs: an amount to the franc between CHF 1,000 and 100,000, a term of 1 to 60 months.
- The same instalment every month — your customer knows from the start what they pay and can plan for it.
- An application in a few minutes, online, without paper and without an appointment.
- Early repayment — your customer can repay the loan in full or in part at any time before the end of the term.
- Clear figures, full legal compliance: all costs disclosed transparently — with no extra work for you. Cashare always treats education loans as consumer loans under the Consumer Credit Act.
No commission — and no cost per loan
Cashare pays you no commission for a referral, and you charge your customer nothing for the financing. What is added to your customer’s interest rate is Cashare’s platform fee. Your benefit lies in the business itself: the order happens, and you receive the full amount instead of instalments — or nothing at all. Your only costs are the setup and monthly fee of your plan — so none with Grow.
Comparison
Why embedded lending from Cashare?
BNPL and factoring were built for other markets. BNPL suits small consumer purchases — not larger orders such as training courses or renovations. Factoring creates administrative work and can increase your default risk. Cashare Embedded Lending is different: you receive the full purchase price in a single payment, 14 days after successful funding, pay no fee per order and have nothing to handle — while your customers repay flexibly over up to 60 months.
| Cashare Embedded LendingRecommended | BNPLBuy Now Pay Later | FactoringSale of receivables | |
|---|---|---|---|
| Merchant fees | None | You pay approx. 1.5–3 % plus a fixed amount per transaction; up to approx. 13 % for interest-free instalment purchases, depending on term | You pay approx. 0.5–3 % plus interest |
| Ticket size | CHF 1,000 – 100,000 | Smaller amounts | CHF 500 – 100'000+ |
| Terms | 1 – 60 months | Shorter terms | 30 – 120 days |
| Payout to you | 100 % in a single payment, 14 days after successful funding | minus fee | 80–90 % immediately, rest on payment |
| Default risk for you | None — with Cashare, standard model without guarantee | None — with the BNPL provider | Partial — with recourse |
| Credit check | Creditworthiness check under the Consumer Credit Act, ZEK and IKO | minimal or none | on the debtor, not on you |
| Admin effort for you | None — Cashare runs everything | low | high — receivables management, reporting duty |
| Regulation | Lender licence, Consumer Credit Act, SRO PolyReg | depending on the product not subject to the Consumer Credit Act (Art. 7 KKG) | contract law |
| Ideal for | Larger orders paid in instalments | Small online purchases | B2B receivables management |
In the standard model without guarantee. Terms for BNPL and factoring differ by provider and contract — check the conditions actually offered to you.
Calculator
What your student pays per month
The argument in the meeting is not the course fee, but the instalment. Preset is a programme of CHF 12’000 over 36 months. Indicative calculation within the 4.8 – 9.9 % effective range.
Non-binding sample calculation (annuity). Actual figures depend on the amount, duration and interest rate of the loan; the creditworthiness assessment and the credit decision rest with Cashare. Important legal notice: granting credit is prohibited if it leads to the over-indebtedness of the consumer (statutory information pursuant to Art. 3 UCA).
References
Swiss training providers have worked this way since 2021
Education was the first industry in Cashare Embedded Lending. These providers offer instalments to their students.
“We have neither the know-how nor the resources for complex long-term financing. Cashare brings the digital platform that handles this need smoothly and in line with the law.”
Case study: the Benedict Schools as “BeneFinancing”
The Benedict Schools, a private education network with locations across Switzerland, have offered instalments under their own name since 2021: the landing page is called BeneFinancing, carries the school’s logo — and Cashare runs behind it. The school receives the course fee in a single payment, students pay the instalments to Cashare; credit assessment, contract, payment processing and dunning stay with us. You get the same model under your own name.

How it works
From your quote to your money
Six steps — your part is at the beginning and at the end.
You give your customer the link to your landing page · you
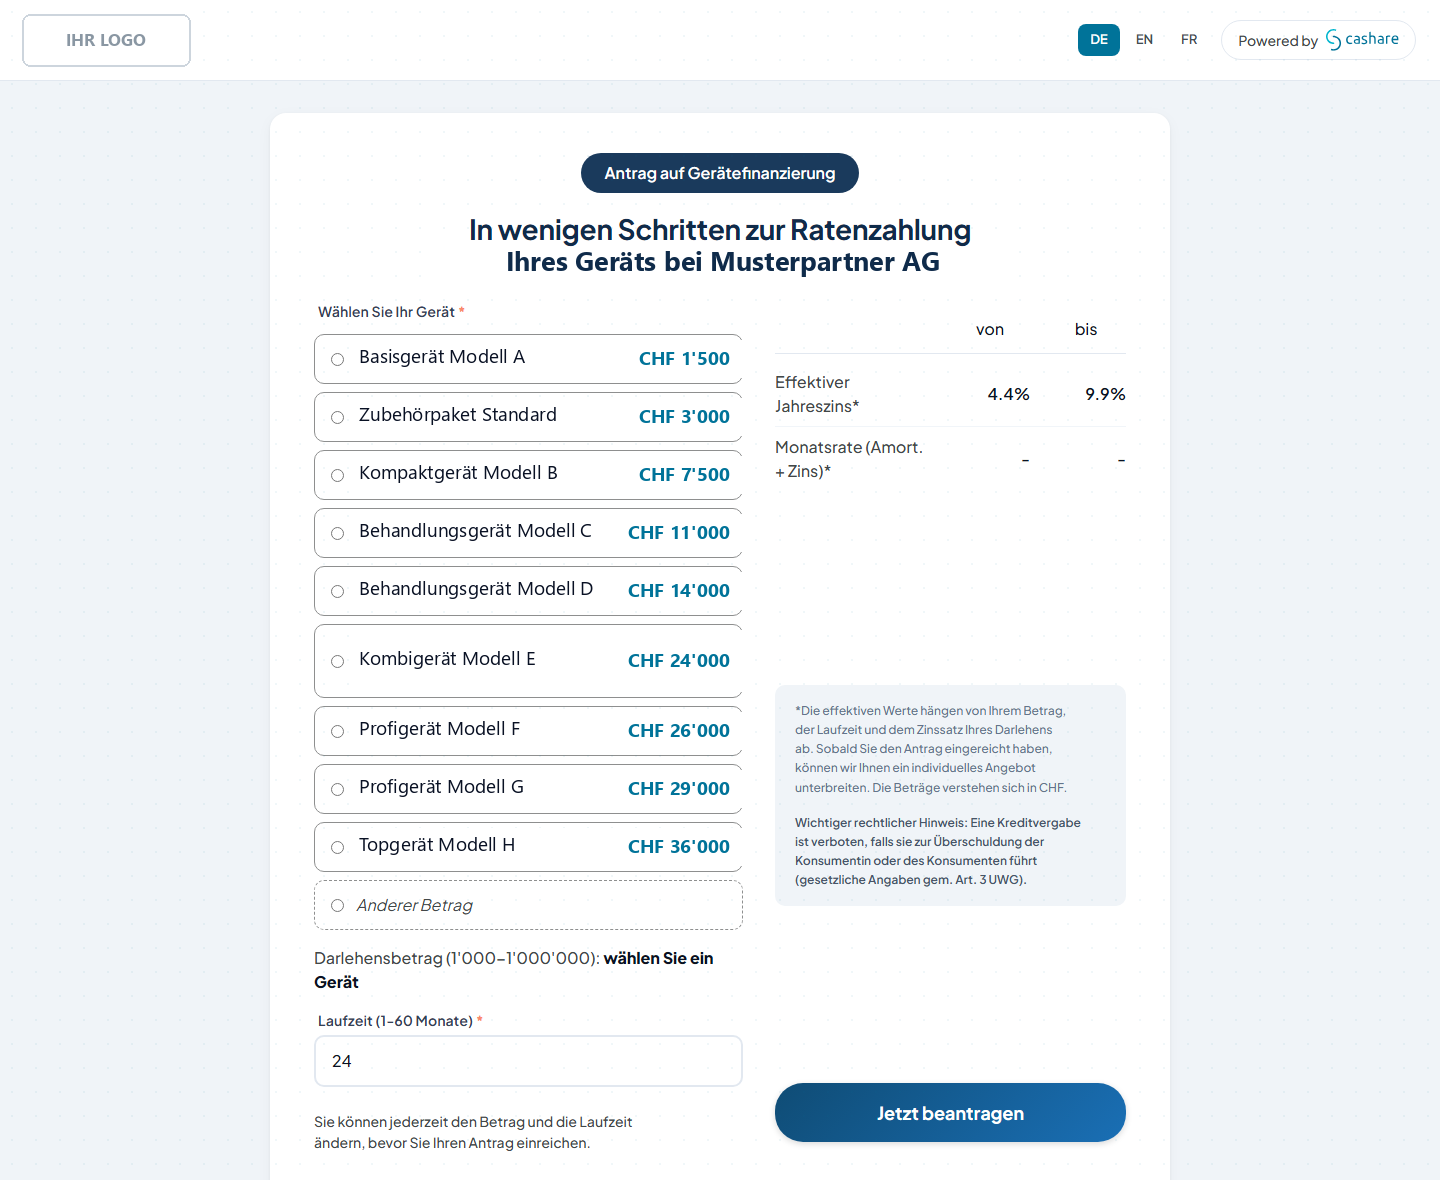
Embedded Lending gives you your own landing page with a personal link — under Cashare branding with Grow, with your logo and company name from Scale. You put the link on your website, on the quote, into the sales conversation or as a QR code on the invoice.
→ Illustration: your landing pageYour customer calculates and applies · customer
On your landing page your customer sees the interest range and the monthly instalment; with Custom they pick directly from your fixed-price catalogue. Then registration, purpose, amount, term. Because the application comes in through your link, it is automatically assigned to you — permanently, including later financings for the same customer.
→ Illustration: your landing pageCashare assesses creditworthiness · Cashare
Our credit team assesses the application and sets the rating. The credit decision rests exclusively with Cashare — required by law, and one less responsibility for you.
The loan is funded · Cashare
The project goes to the marketplace and investors fund it. You do not have to do anything.
Once the withdrawal period has expired, the payout reaches you · Cashare
The whole loan amount to your account as soon as your customer’s right of withdrawal has expired: 14 days after successful funding — under the Consumer Credit Act. One-off precondition: completed onboarding and a registered IBAN.
You deliver, your customer pays in instalments · you
Your work is paid for. The monthly instalments go from your customer to Cashare — that no longer concerns you.
Loan product
What your students get — depending on the amount
Education is almost always financed privately. The amount determines the legal basis, not the process.
Consumer loan under the CCA — up to CHF 80,000
The standard case in education financing.
- Effective annual rate of 4.8 to 9.9 %, term of 1 to 60 months, amount in steps of one franc — exactly the course fee.
- Payout 14 days after successful funding — the period is the right of withdrawal under the Consumer Credit Act.
- Affordability assessment under the CCA with budget calculation and ZEK and IKO enquiry — done by Cashare, not by you.
- No mortgage, no guarantee and no security over the diploma.
Private loan above CHF 80,000
For executive programmes and multi-year degrees.
- No legal CCA obligation, but Cashare applies the CCA anyway, identical process — same enrolment, same landing page, same assessment.
- Payout also 14 days after successful funding; the 14-day right of withdrawal applies as under the CCA.
- Rate range 4.8 to 9.9 % effective, depending on creditworthiness and term.
- Several applications possible when a degree is paid in semester or annual tranches.
We make the credit decision, not you.
Your adviser does not have to assess creditworthiness or prepare a budget — the law assigns that to us and it stays that way. You point to the financing, Cashare assesses affordability and creditworthiness and decides. You receive no commission and pay no fee per enrolment.
Your students pay the instalments to Cashare. You are named as the payee in the loan agreement and have nothing to do with repayment — not even if a course is abandoned.
Plans
Start without risk, switch any time
Start for free and scale as your business grows. You can move up a tier at any time.
Grow
Entry level · for small businesses
per month CHF 0
Your own landing page under Cashare branding, with no IT effort. With starter kit, cockpit and email support. Interest for private customers 4.8 – 9.9 %.
Start for freeScale
More closed deals · for mid-sized businesses
per month CHF 259
Everything in Grow, fully in your branding. With financing calculator, sales training and key account manager. Optionally with a guarantee and a uniform fixed rate.
Book a demoScale Plus
Fully integrated process · for growing teams
per month CHF 299
1 employee included, CHF 100 per additional person
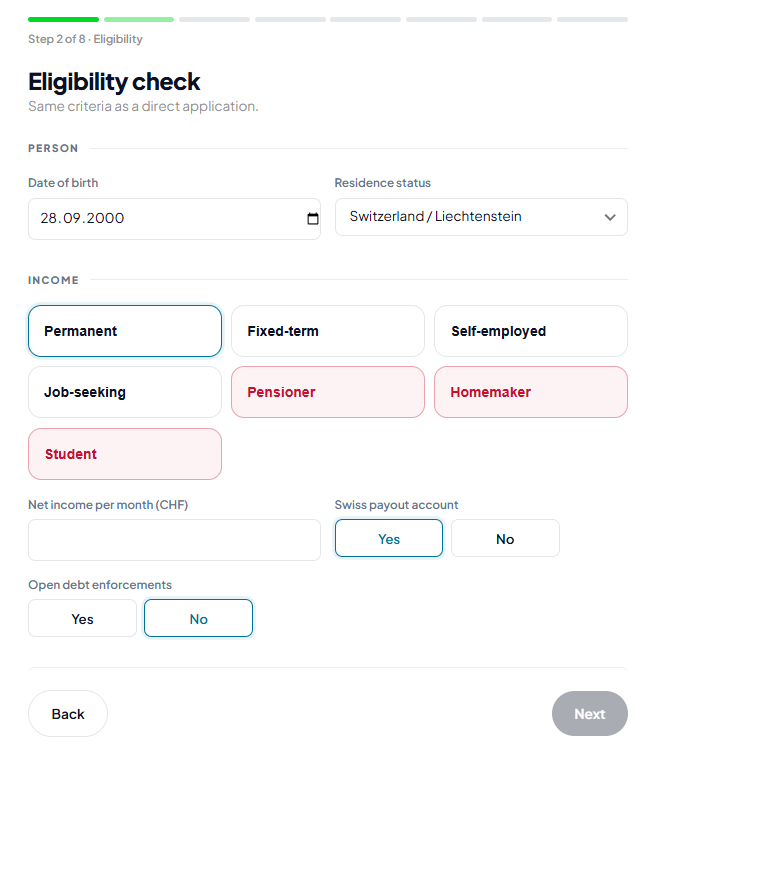
Everything in Scale, plus the partner portal: you enter the loan application for your customer yourself. Individual login per employee, customer list, project overview and extended analytics. With employee training; AMLA duties can be taken over*.
Book a demoCustom
Enterprise solution · for large providers
per month CHF 499
1 employee included, CHF 100 per additional person
Everything in Scale Plus, connected to your systems through an interface. Own fixed-price product catalogue in real time, individual product design and 0 % financing with self-funding.
Request a consultationWith Custom the setup fee is a starting value; the final amount depends on the agreed scope. * Taking over the due-diligence duties requires annual AMLA training, which Cashare provides. There is no fee per loan; only in the guarantee model are collection cases charged at cost.
What each tier includes
| Feature | Grow | Scale | Scale Plus | Custom |
|---|---|---|---|---|
| Own landing page | with Cashare branding | 100 % your branding | 100 % your branding | 100 % your branding |
| Cockpit with your key figures | ✓ | ✓ | ✓ | ✓ |
| Payout to your account | ✓ | ✓ | ✓ | ✓ |
| Customer list and project overview | — | — | ✓ | ✓ |
| Enter applications for your customers yourself | — | — | ✓ | ✓ |
| Logins for employees | — | — | ✓ | ✓ |
| Guarantee model with fixed rate | — | uniform, fixed | uniform, fixed | uniform, fixed |
| Financing calculator on your page | — | ✓ | ✓ | ✓ |
| Sales training and promotional material | — | ✓ | ✓ | ✓ |
| Own product catalogue with fixed prices | — | — | — | via interface, in real time |
| 0 % financing for your customers | — | — | — | with self-funding |
| Due diligence (AMLA) | by Cashare | by Cashare | can be taken over* | can be taken over* |
| Support | Key account manager | Key account manager | Key account manager |
In the partner portal, from Scale Plus
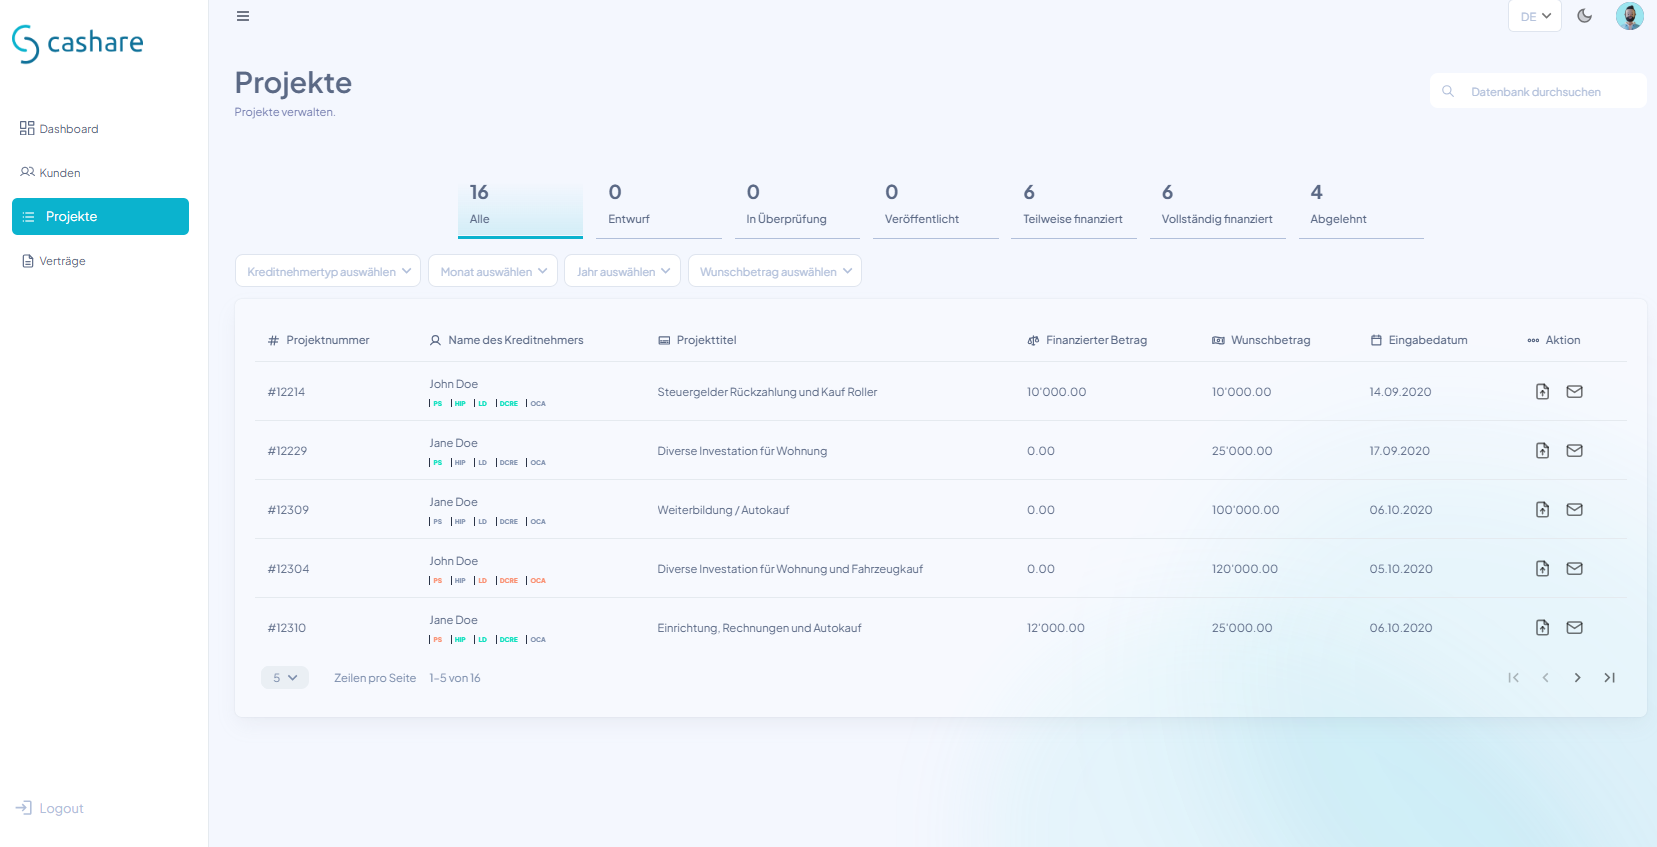
One team, a clear view
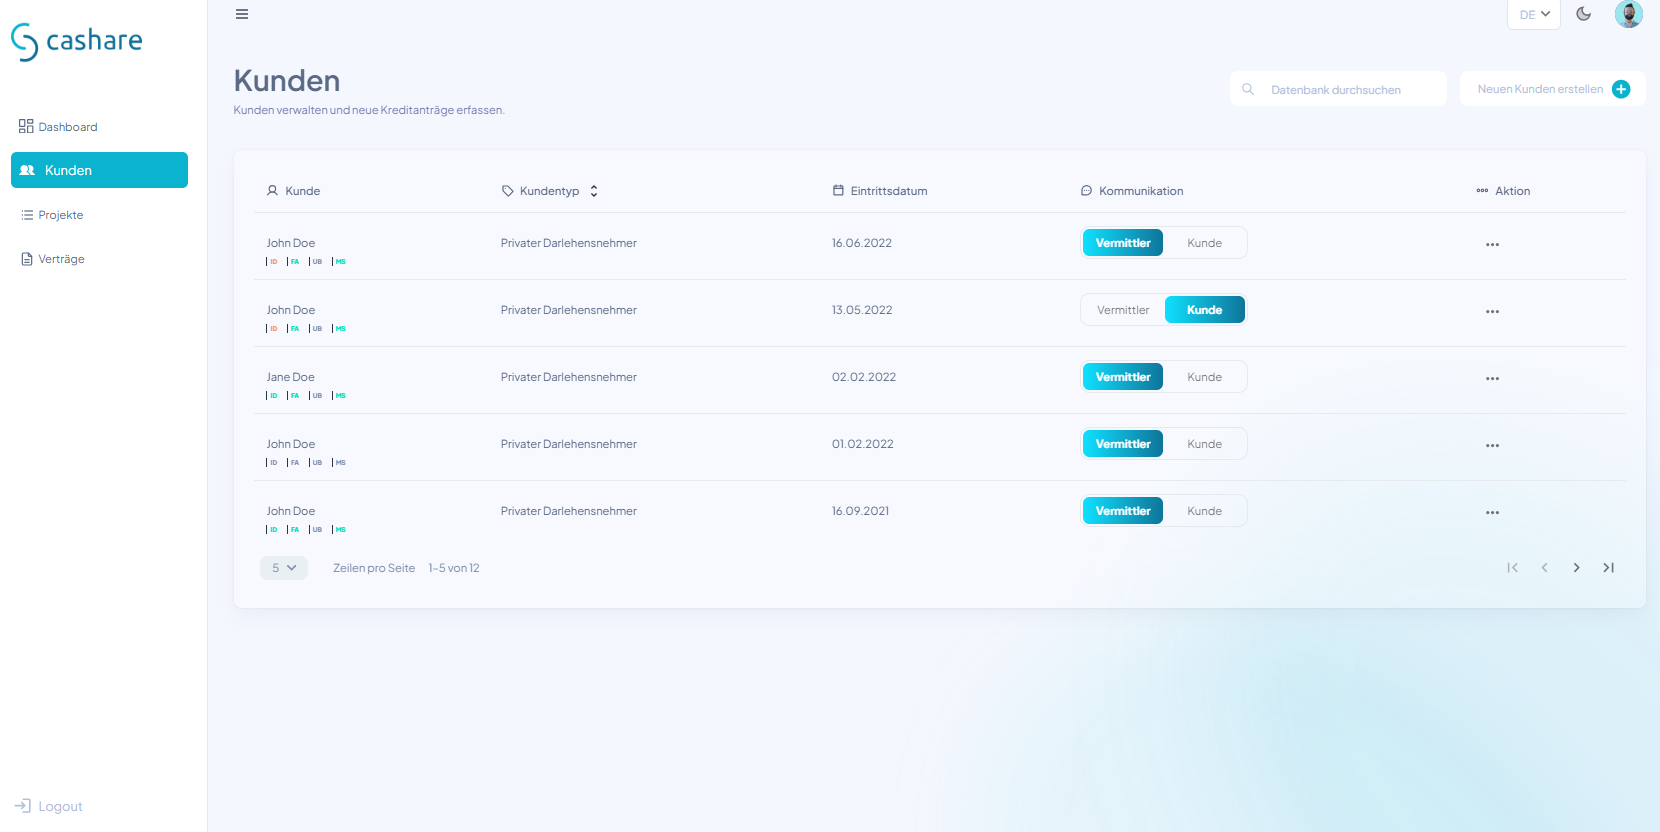
From Scale Plus you invite your employees yourself; each person sets their own password. An employee sees only their own customers, the main account sees everyone. Beyond your agency’s boundary nobody sees anything — no other partner either.
Honestly
When we fit — and when we do not
Financing that does not fit your offering costs both sides time. Hence the boundaries up front — specifically for training providers.
We fit if …
- Your course fees start at around CHF 1,000 and reach five figures for degree programmes.
- your customers may need more than three years to pay — up to 60 months.
- you want to appear under your own brand, not a payment provider’s.
- you do not want to give up margin per order.
We do not fit if …
- you want to finance baskets below CHF 1,000 — invoice-purchase and BNPL providers are built for that.
- you need a decision in seconds at checkout: with us a credit team reviews the case and the project is funded via the marketplace.
- your customer must pay interest-free and you want to carry the cost: that is the merchant-fee model. With us, 0 % models exist only in the Custom plan, as a specifically agreed sales promotion.
- you are looking for a ready-made shop integration for online checkout. Our route runs through your landing page.
Guarantee · option from Scale
Better terms for your customers — with your guarantee
If, as a legal entity, you guarantee the loans you refer, the interest rate is no longer negotiated on the marketplace but agreed as a fixed rate for you — regardless of the individual customer’s rating. That makes your offer cheaper and more predictable for your customers.
How it works
- A separate framework agreement between you and Cashare governs the guarantee — not your customer’s loan agreement.
- From your financial figures Cashare derives a maximum amount, the Gross Debt Capacity (GDC): the total amount you can guarantee. It is reassessed annually.
- The maximum amount is only used up by the outstanding balances of the guaranteed loans — every instalment returns capacity.
- You receive a register of all guaranteed loans and their status.
- We continue collections for you. Once you have paid, our collections team keeps pursuing the outstanding debt with the customer — from then on on your behalf. Whatever comes in goes to you; collection costs incurred from that point are charged to you.
What you should know
- Your customer remains fully liable for their debt; the guarantee protects Cashare and the investors.
- The guarantee does not appear in your customer’s loan agreement and is not reported to ZEK as collateral.
- If a loan defaults after unsuccessful dunning, Cashare claims the outstanding balance from you, with a 20-day payment period.
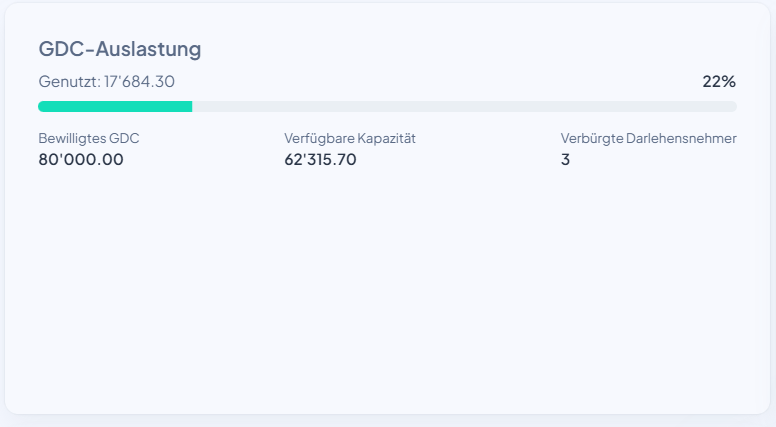
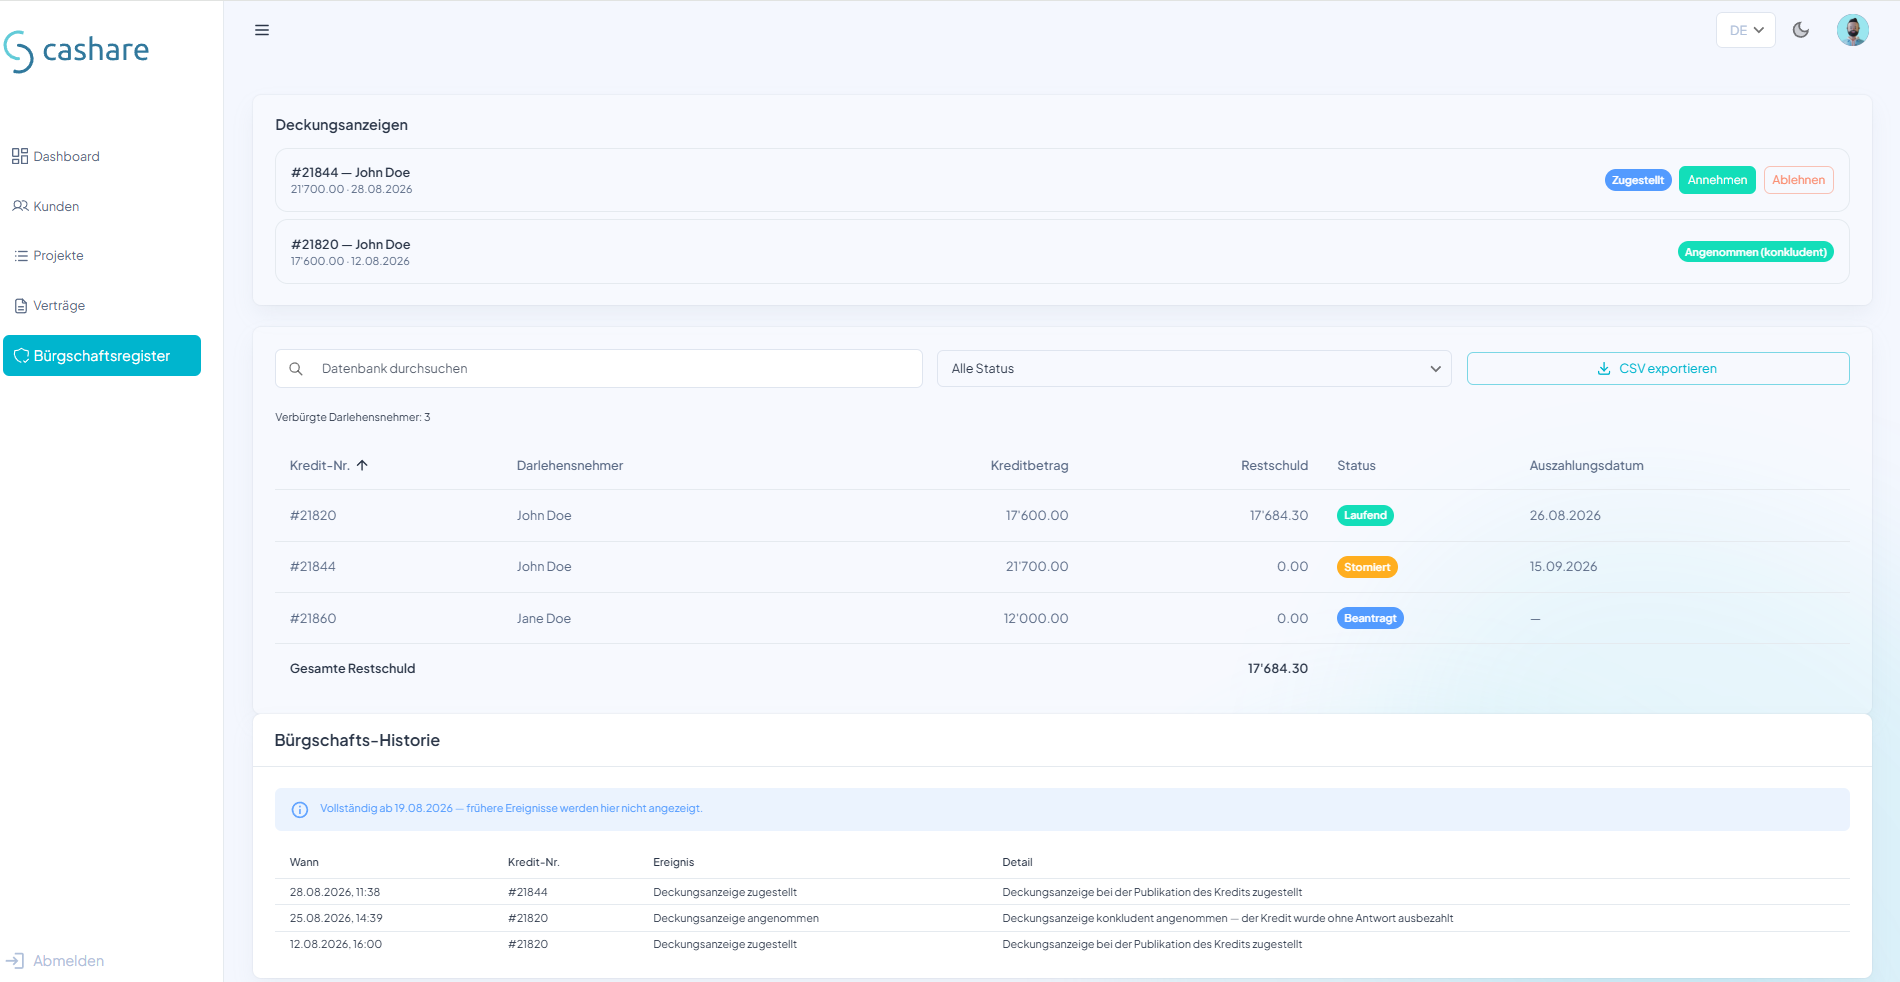
Guarantee option: availability depends on credit quality and on your company’s Gross Debt Capacity (GDC). It is granted after an individual review by Cashare under the partnership agreement.
Onboarding
What we need to get started
With Grow onboarding starts immediately; with the other plans it usually takes only a few days once the documents are complete.
- Your company
- Commercial register entry, company name and business address. That address later becomes your billing address.
- Contact person
- One authorised signatory as the main contact.
- Identification
- Copy of an ID document, Form K on beneficial ownership, a CHF 5 transfer from your company account and a copy of an invoice confirming the address.
- Bank details
- The IBAN the payouts go to. Without an IBAN on file, no loan is paid out.
- Your logo
- For the landing page, as an image file or an image URL.
- Training
- From the “Scale Plus” plan there is annual training on due-diligence duties for everyone who identifies customers.
Where the line is drawn
You run the conversation, you know your customer, you submit the application. The credit decision and the go-live are made exclusively by Cashare — after the creditworthiness assessment and with a rating. That applies to every tier.
Frequently asked
What partners ask us most often
Here are some questions and answers. We are happy to help with anything else.
Talk to a person
Question not listed? We will go through it with you.
+41 41 558 48 88 partner@cashare.ch Get in touchWhat is embedded lending?
Embedded lending means the financing is built directly into your offer: your customer finds the instalment option where they buy. They apply on your landing page, the loan comes from Cashare. You receive the full invoice amount, your customer pays the instalments to Cashare.
What does Embedded Lending cost?
Four plans: Grow free (CHF 0 setup, CHF 0 per month), Scale CHF 1'999 and CHF 259 per month, Scale Plus CHF 2'499 and CHF 299 per month, Custom from CHF 6'000 and CHF 499 per month. There are no additional costs per loan.
How long until I get my money?
If your customer is a private individual, the payout happens 14 days after successful funding: they can withdraw from the loan agreement within 14 days — under the Consumer Credit Act. After that the whole amount arrives in a single payment in your account.
How is this different from BNPL providers?
In the widespread merchant-fee model the financing is interest-free for your customer and you pay a percentage of the invoice amount per order. With Cashare you pay a fixed monthly fee and nothing per order; the cost is carried by your customer through the interest rate. In return we finance amounts up to CHF 100,000 and durations up to 60 months. If you want to offer your customer 0 % and carry the cost yourself, that is possible in the Custom plan as an agreed sales promotion.
And how is this different from factoring?
Factoring solves a different problem. There you sell your outstanding receivable to a factor and receive the amount less a deduction; your customer gets no instalment option, their payment terms stay the same, and reporting receivables and reconciling payments stay your job. Factoring helps your cash flow when customers pay late. Cashare addresses the case before that: your customer cannot or does not want to pay the amount in one go. They pay instalments to Cashare, you receive the full amount 14 days after successful funding — with no deduction and no admin afterwards.
Do I receive a commission?
No. Cashare pays no remuneration for a referral, and you charge your customer nothing for the financing. The mark-up on the nominal rate is Cashare’s platform fee. Your benefit is the order and the full payment.
What happens if a student drops out of the course?
The loan agreement is between your student and Cashare and remains in force — whether the course is attended, abandoned or the exam failed. Your payout is not reclaimed as a result. A refund under your own course terms is settled directly with the student as before; Cashare is not party to that arrangement.
What happens if my customer’s application is declined?
You incur no cost and no effort. Not every application is approved — the creditworthiness assessment is required by law and the decision rests with Cashare. In the project overview you see the status of each application, declines included, and in the cockpit the quality of your submissions over time.
Do I carry a default risk?
Not in the standard model without a guarantee: instalments and dunning are a matter between your customer and Cashare. If, from the Scale plan onwards, you voluntarily choose the guarantee variant, you guarantee the loans you refer and in return get a fixed agreed rate for your customers.
Which amounts and durations are possible?
Loans from CHF 1,000 to CHF 100,000, in steps of one franc, with durations from 1 to 60 months. That way the loan amount matches your invoice amount exactly.
Who decides on the loan?
Cashare alone, after the creditworthiness assessment and with a rating. This is required by law and takes the responsibility off your shoulders. Loans to private individuals up to CHF 80,000 without a mortgage are subject to the Consumer Credit Act.
Is this a student loan or a grant?
Neither. What is financed is an ordinary consumer loan under the Consumer Credit Act in your student’s name — with instalments from the first month, without deferred interest during the course and without any dependence on grades or the diploma. Cashare receives no examination or performance data from you; the affordability assessment looks at income and budget, not at the programme. Cantonal grants and education allowances can be applied for independently.
How long does onboarding take?
With Grow it starts immediately. With the other plans usually a few days, once the documents are complete: commercial register entry, authorised contact person, identification, IBAN and logo.
Related industries
If your offering is not education
Embedded Lending is the same, the loan products differ. This page is one of nine industry pages; the Embedded Lending head page shows them side by side.
Medical and dental practices
Treatments and dental work the patient pays in instalments — same process, different invoice.
Equipment and machinery
Devices, instruments and training equipment at fixed prices in the catalogue on your landing page.
Trades and construction
When your client is a company rather than a private household. Payout tied to project milestones.
Next step
Start with Grow — free and without commitment
You register your company, we activate Grow, you have your landing page. No meeting and no quote needed.
For Scale, Scale Plus, the guarantee or a custom model, get in touch directly — then we will talk about your case.
Thank you — we will get back to you within one business day at the address you gave. Questions in the meantime: partner@cashare.ch